

Gold IRAs Explained: What the Rules Allow and What They Cost
An annual account fee is easy to spot. The extra amount built into a gold coin's price is less obvious, and it can outweigh years of those fees. That difference sits at the heart of what a gold retirement account costs.
A gold individual retirement account (IRA) is an ordinary retirement account holding physical metal. It is usually self-directed: the owner chooses the investments. The account determines the tax treatment; gold remains the investment. Federal law limits which metal qualifies and who must hold it.1 A custodian runs the account, a dealer sells the metal, and a vault accepted by the custodian stores it. Their roles are separate, and their charges reach the account in different ways.
The Safeguard Metals case shows how expensive that purchase can become. On November 20, 2025, the Commodity Futures Trading Commission (CFTC) and 30 state regulators announced a final judgment against the dealer and its owner: $25.6 million in restitution and an equal civil penalty.2 Most of the roughly $68 million collected was retirement savings. Customers were told silver coin markups would be no more than 23%; the average was 71%.3
The numbers at a glance
The gold stays in custody while it stays in the IRA
Money usually enters by contribution or transfer from another retirement account. The custodian pays the dealer on the owner's instructions, and the dealer sends the metal to the depository. The owner directs the purchase but cannot take personal possession while the metal remains in the IRA. An authorized distribution can send the metal to the owner; its tax treatment depends on the account and distribution.
How gold moves into an IRA
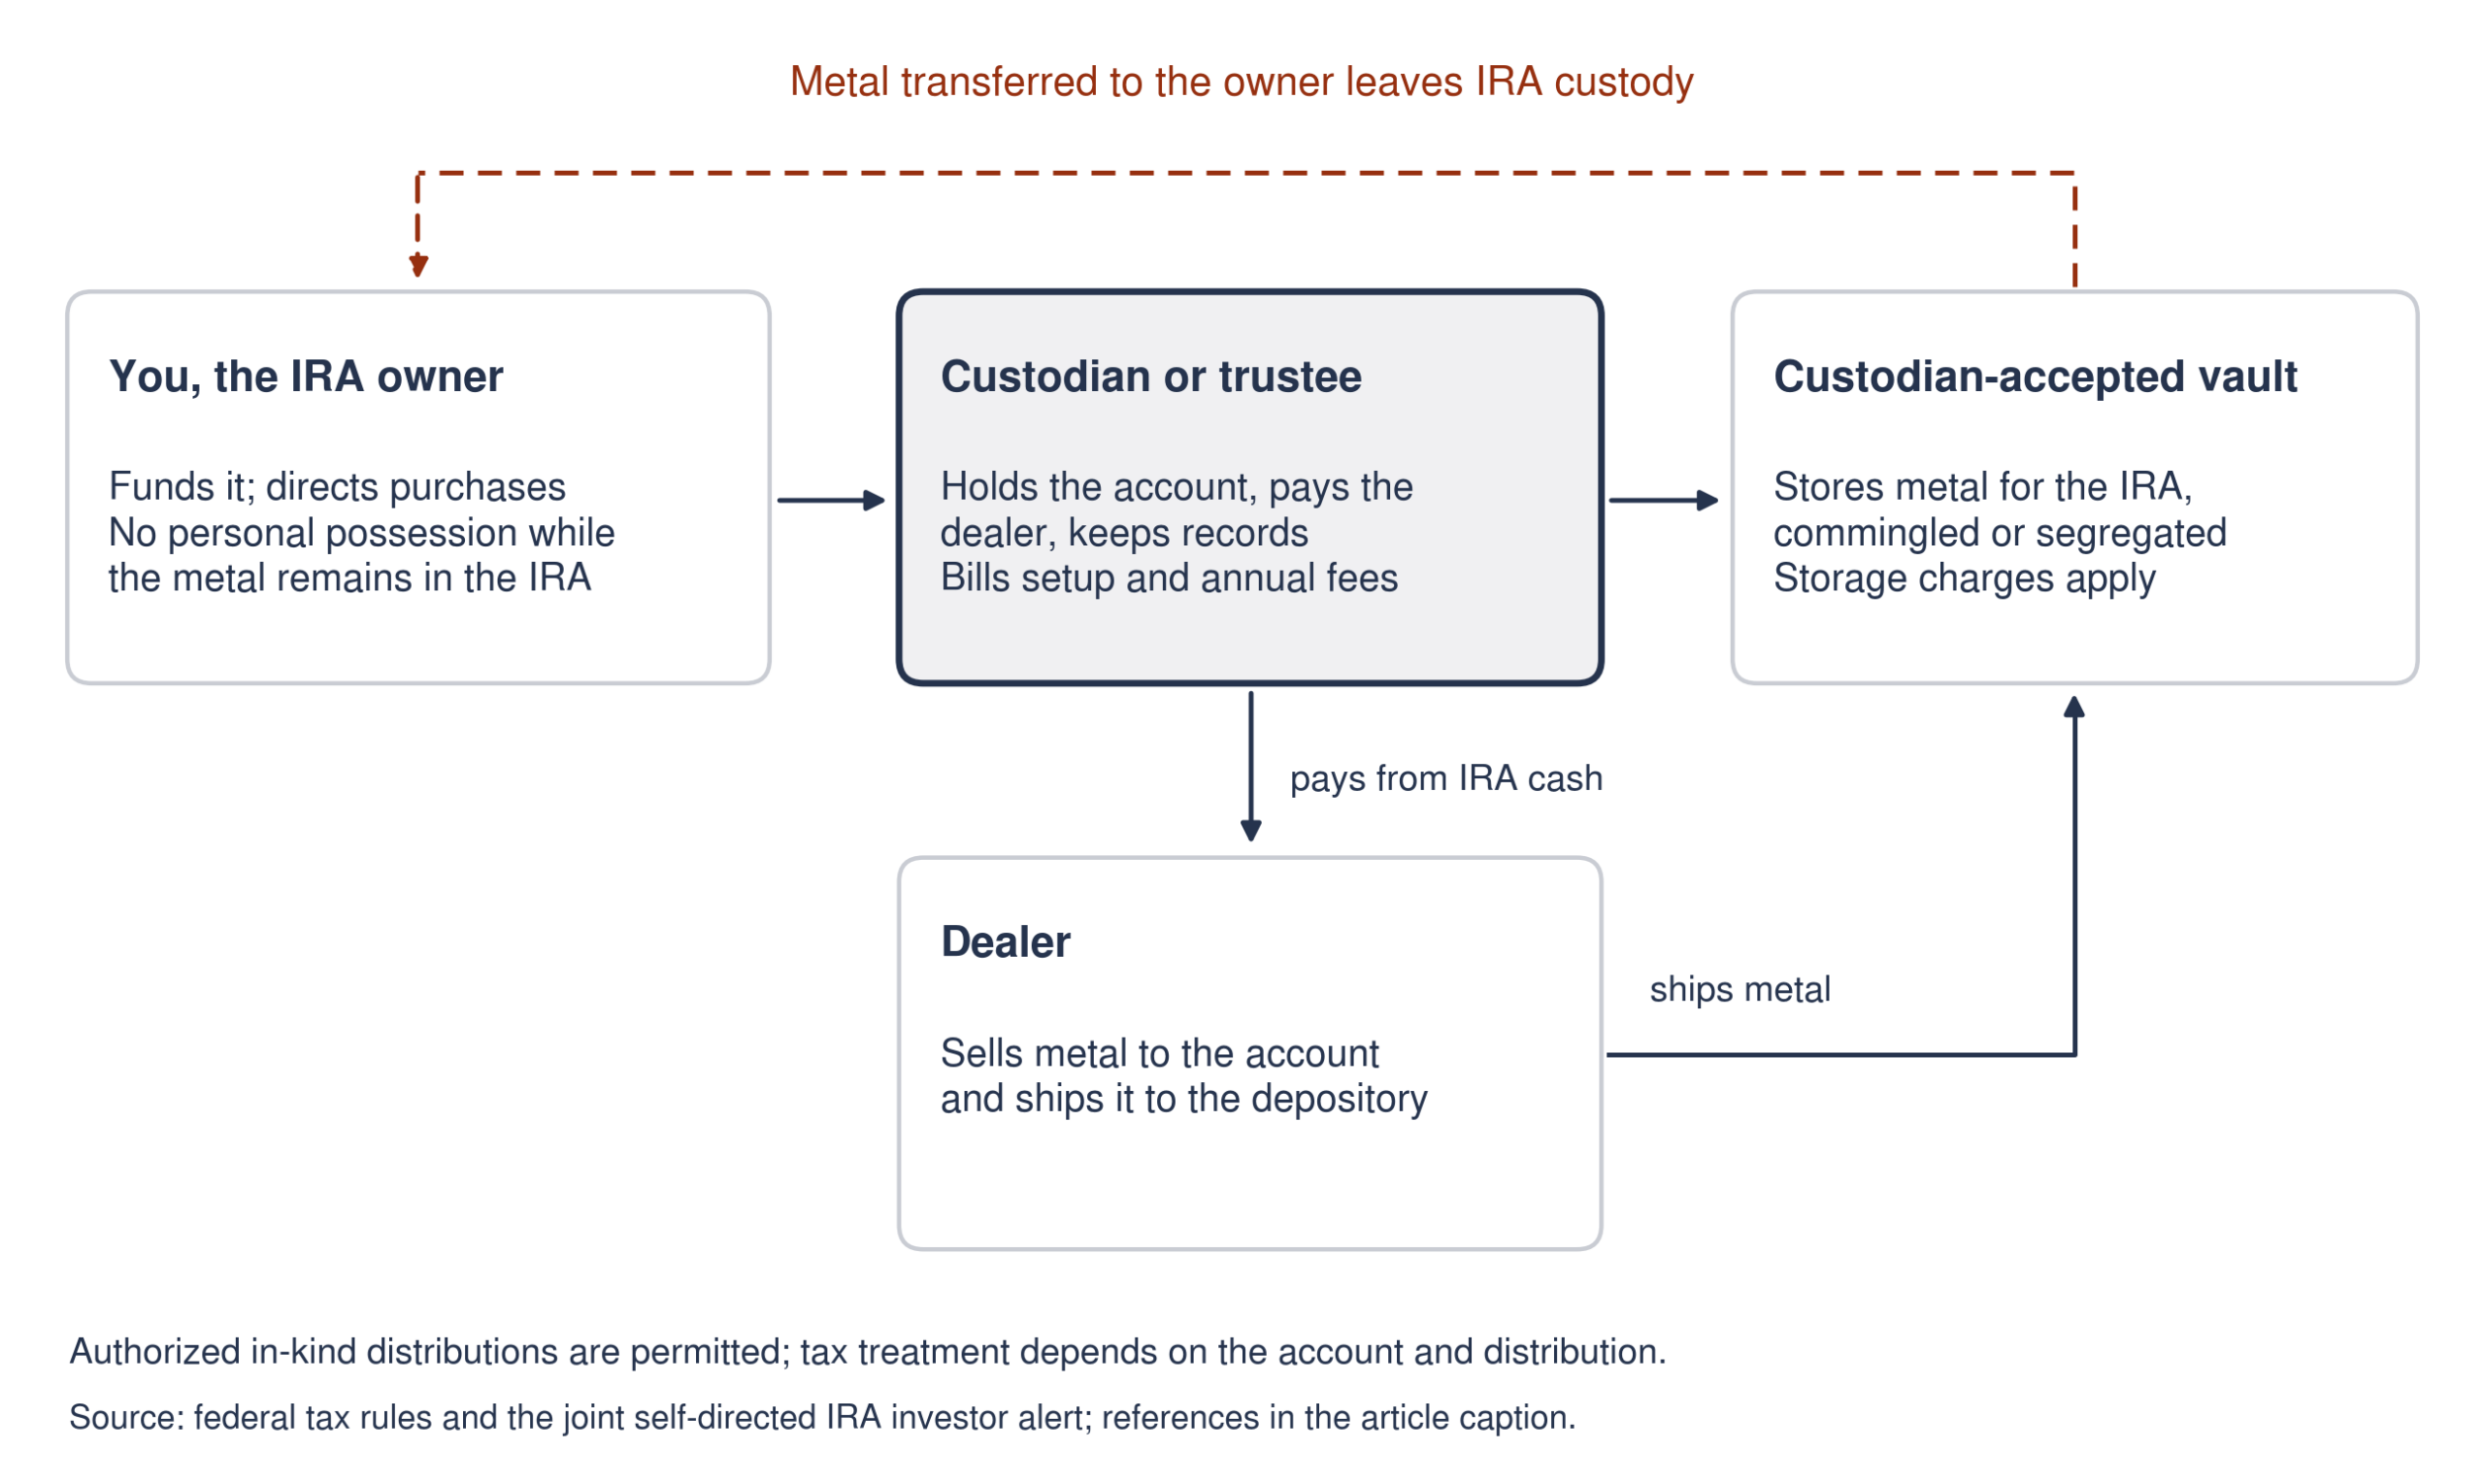
The owner directs purchases; custody stays with the trustee and vault until a distribution.1, 8
The metal must also qualify. The Internal Revenue Service (IRS) generally treats an IRA's purchase of collectibles, including metals and coins, as a distribution: money taken out for tax purposes. Exceptions cover specified United States coins, state-issued coins, and bullion meeting fineness requirements and held by a bank or approved nonbank trustee.1 The coin exceptions and bullion standards are distinct.
GoldStar Trust's list gives fineness standards of .9950 for gold, .9990 for silver and .9995 for platinum and palladium. It excludes rare, certified or graded coins and the South African Krugerrand.9 Custodians' restrictions can differ; a provider's list does not replace the statutory exceptions.
Eligibility doesn't create a home-storage exception. In McNulty v. Commissioner (2021), an owner kept American Eagle coins bought through an IRA-funded limited liability company (LLC) in her home safe. The Tax Court treated her possession as taxable distributions of $374,000 in 2015 and $37,380 in 2016.10
The purchase price starts a second bill
Custodian schedules show setup, administration, storage, trade and closing fees. The dealer's markup is built into the metal's price. A purchase premium is paid immediately; annual account charges accumulate over time.
In its August 2020 advisory, the CFTC described bullion premiums of 5% to 10% above spot, the metal's market price, and numismatic, or collector, coin premiums of 40% to 200% above spot.7 Those are historical figures, not current quotes. The advisory also cited a complaint involving nearly $150,000 in commissions and fees on a $300,000 rollover.
The illustration follows bullion with a $100,000 spot value for 10 years, with the metal price flat. The purchase premium lifts its starting cost to $105,000 to $110,000 before account fees. Each row selects low and high charges across three providers, so neither case is one provider's quote.4, 5, 6, 7
The premium can rival a decade of account fees
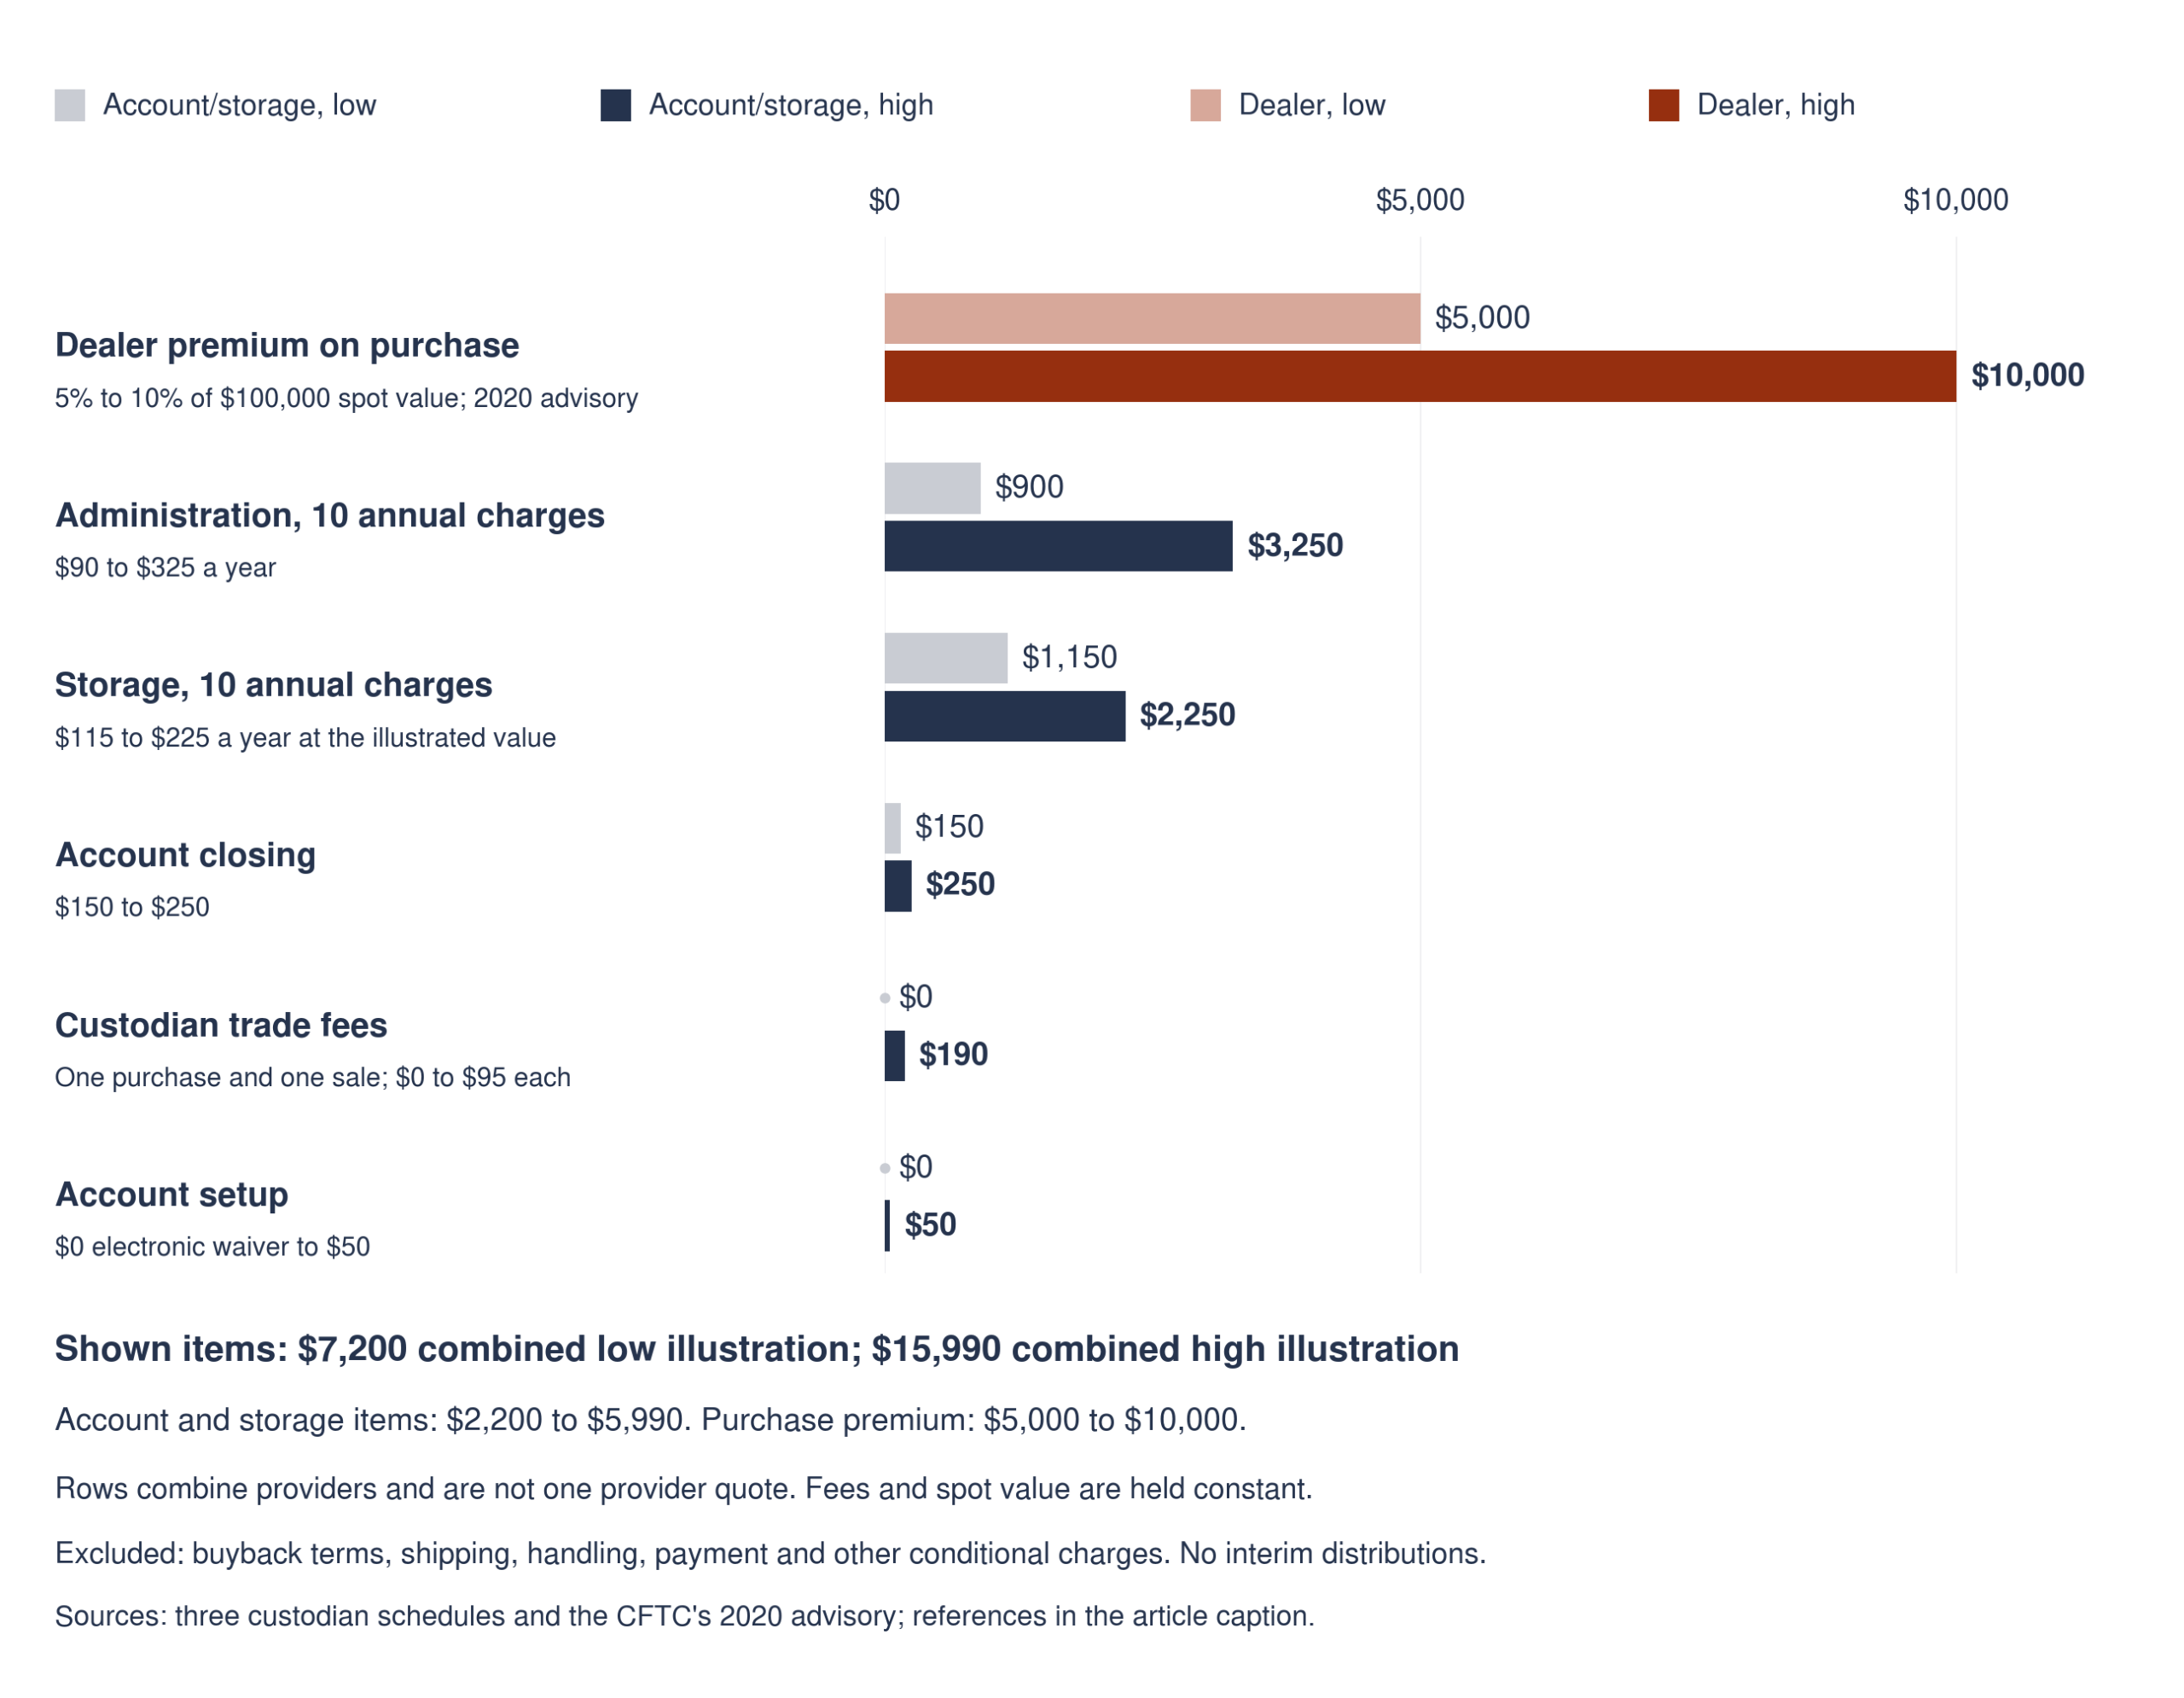
Hypothetical: $100,000 spot value of bullion, flat metal price, fixed fees and ten annual charges. Buyback discounts and other conditional costs are excluded.4, 5, 6, 7
Includes STRATA's online setup waiver and GoldStar's free trades and $150 termination fee. STRATA separately lists $35 depository handling; its schedule does not make that charge automatic on every trade.4, 5
The account and storage items total $2,200 to $5,990. The purchase premium adds $5,000 to $10,000, bringing the shown total to $7,200 to $15,990. In this model, the charge paid on day one can rival a decade of account costs.
Flat fees weigh more heavily on smaller balances: $90 to $325 in administration is 0.4% to 1.3% of $25,000 each year, before storage. Some fees scale with value: Vantage charges storage at 0.20% of account value, with a $150 minimum; GoldStar adds 0.18% on metal above $125,000.4, 6
Storage type matters too. Commingled storage pools like items; segregated storage keeps an owner's specific metal apart. Segregated storage costs more on the two cited schedules pricing both.4, 5
Selling introduces another price. The CFTC's 2024 fraud guidance describes buy-sell spreads of 30% to 300% or more.11 That is scam guidance, not a typical bullion buyback discount. The cited sources don't establish a typical discount, so the illustration leaves that cost out.
Custody doesn't establish a fair price
Safeguard wasn't the only case. The CFTC alleged that Red Rock Secured routinely charged coin markups of about 100% to 130% over its acquisition cost, against stated ranges of 4% to 29% or 1% to 5%. About $34.4 million of customers' $61.8 million went to markups.12
An April 2024 Securities and Exchange Commission (SEC) consent judgment ordered the company to pay $50.15 million in disgorgement, plus interest and a $10 million penalty.13
The SEC, North American Securities Administrators Association and Financial Industry Regulatory Authority (FINRA) explained custodians' limited role in a 2023 joint alert: they hold and administer assets, without evaluating investment quality or legitimacy.8 Another CFTC case alleged that custodians released funds against fraudulent dealer invoices.14 A custodian's involvement does not establish that a purchase was sound.
The account changes how the gold is taxed
The CFTC notes there are no special tax breaks for self-directed IRAs.11 Inside a traditional IRA, tax is deferred until money or metal leaves. Taxable distributions are generally ordinary income, excluding the return of after-tax contributions; qualified Roth IRA withdrawals can be tax free.15 Outside an IRA, net long-term collectibles gains, generally on assets held more than one year, face a maximum 28% capital-gains rate.16
Bullion pays no interest or dividends. Its return comes from price changes, less costs. Bills still arrive in flat years: Vantage invoices its administration fee on each funding anniversary. Fees can be met from account cash, outside money or metal sales.6
Traditional IRA owners also face required minimum distributions (RMDs): age 73 for those reaching it now, or 75 for those born in 1960 or later.17 A shortfall can face a 25% excise tax.18 Reduction to 10% requires the missing amount to be distributed from the same plan and a return reflecting the tax to be submitted within the statutory correction window, which can close before two years.19 Original Roth IRA owners have no lifetime RMDs.15
A metals account can distribute cash or the metal itself. Property is reported at fair market value on the distribution date.20 GoldStar lists a $75 partial-transfer/distribution-in-kind fee; $10 plus shipping cost may also apply.4 Later long-term gains on distributed coins fall under the collectibles rate.16
The rules govern what can enter the account and how it is held. They don't establish whether the metal was reasonably priced. The tax treatment, account charges and dealer's buying and selling prices all shape the result. An IRA-eligible label answers only the first part of that story.
Frequently asked questions
Can metal held in a gold IRA be stored at home? No. The bullion exception requires a bank or approved nonbank trustee to keep physical possession1. In the 2021 McNulty case, the Tax Court treated IRA coins kept in an owner's home safe as a taxable distribution, even though the coins had been bought through an IRA-funded LLC10.
What are typical gold IRA fees? Three custodians' published schedules show a setup fee of $0 to $50, $90 to $325 a year in administration and $115 to $225 a year for storage at the illustrated $100,000 value, with segregated storage costing more on two of the three schedules4, 5, 6. The dealer's premium is separate and, in the hypothetical above, can exceed a decade of those fees.
Can an IRA hold collectible or graded coins? Generally not. An IRA's purchase of a collectible is treated as a distribution unless it fits the coin or bullion exceptions1, and custodians publish lists of coins they exclude9.
Can required minimum distributions be taken in metal? Yes. Metal can leave the account in kind, and its fair market value on the distribution date is what gets reported20. For traditional IRAs, required distributions start with the year the owner reaches the applicable age: 73 for those reaching it now, or 75 for those born in 1960 or later17.
Sources & Disclosure
1 Investments in collectibles in individually directed qualified plan accounts. Internal Revenue Service, last reviewed July 3, 2026; collectibles rule and the coin and bullion exceptions, including trustee possession. 2 CFTC, 30 State Regulators Obtain Over $51 Million in Sanctions, Restitution for Victims in California Precious Metals Fraud. CFTC, November 20, 2025; Safeguard Metals final judgment, $25.6 million restitution and $25.6 million penalty. 3 CFTC and State Regulators Enter Consent Order with California Precious Metals Dealer in $68 Million Fraud Targeting the Elderly. CFTC, October 25, 2023; the $68 million, mostly retirement savings, and the 71% average versus 23% stated maximum markup. 4 Fee Schedule, Rev. 01/2026. GoldStar Trust Company, January 2026; precious-metals administration, storage, value-based storage and in-kind distribution fees. 5 IRA Fee Schedule, effective September 1, 2026. STRATA Trust Company; precious-metals tier setup, annual, storage, transaction and closing fees. 6 Precious Metals IRA Fee Schedule. Vantage IRAs, last modified March 26, 2026; setup, annual, storage, transaction and termination fees and billing timing. 7 CFTC Advisory Warns Customers to Carefully Assess Precious Metals Pitches Touting CARES Act Rules. CFTC, August 4, 2020; bullion premiums of 5% to 10%, numismatic premiums of 40% to 200%, nearly $150,000 in commissions and fees on a $300,000 rollover. 8 Investor Alert: Self-Directed IRAs and the Risk of Fraud. SEC Office of Investor Education and Advocacy, North American Securities Administrators Association and FINRA, February 7, 2023; custodians' limited role. 9 IRA Allowable Metals. GoldStar Trust Company, accessed November 5, 2026; fineness standards and excluded coins. 10 McNulty v. Commissioner, 157 T.C. No. 10. United States Tax Court, November 18, 2021; custody holding, distribution amounts and quotation. 11 Lies Versus Facts: The Truth Behind Gold and Silver IRA Scams. CFTC Office of Customer Education and Outreach, March 20, 2024; buy-sell spread, eligible coins, no special tax breaks. 12 The CFTC and State Regulators in California and Hawaii Charge Los Angeles Area Precious Metals Dealer in Ongoing $61 Million Fraud Targeting the Elderly. CFTC, May 15, 2023; Red Rock Secured markups of about 100% to 130% versus stated ranges, $34.4 million of $61.8 million. 13 Red Rock Secured LLC, Sean Kelly, Anthony Spencer, and Jeffrey Ward, Litigation Release No. 25996. Securities and Exchange Commission, May 7, 2024; April 23, 2024 consent judgment amounts. 14 CFTC Charges Dallas and Los Angeles Area Precious Metals Dealers in Ongoing Fraud Scheme Garnering Over $7 Million from Retirement Accounts. CFTC, September 26, 2023; IRA custodians transferring funds to dealers against invoices the CFTC alleged were fraudulent. 15 Publication 590-B (2025), Distributions from Individual Retirement Arrangements. Internal Revenue Service; traditional and Roth distribution tax treatment, after-tax basis and no lifetime RMDs for original Roth IRA owners. 16 Topic no. 409, Capital gains and losses. Internal Revenue Service, last reviewed November 9, 2026; 28% maximum rate on long-term collectibles gains. 17 Treasury regulations, 26 CFR §1.401(a)(9)-2(b)(2) and §1.408-8(a)(3), (b)(1). Electronic Code of Federal Regulations, accessed November 12, 2026; applicable distribution ages, including age 75 for those born in 1960 or later, and application to IRAs. 18 Retirement plan and IRA required minimum distributions FAQs. Internal Revenue Service, last reviewed January 29, 2026; required distributions and 25% or 10% excise tax; cohort ages and correction-window conditions are detailed in the cited regulations and statute. 19 Internal Revenue Code §4974(a), (e). Office of the Law Revision Counsel, United States House of Representatives, accessed November 12, 2026; 25% shortfall tax, 10% reduction conditions and the statutory correction window. 20 Instructions for Forms 1099-R and 5498 (2026). Internal Revenue Service, 2026; fair market value of distributed property on the date of distribution.
Wealthion is a dba of Greylock Peak Investments, a registered investment adviser. This article is general information only. It is not investment advice or an offer or solicitation, and it is not tailored to your circumstances. Guests’ views are their own and may not reflect those of Wealthion. Wealthion has not verified guest statements, including any performance figures. Investing involves risk, including loss of principal, and past performance does not guarantee future results. Wealthion refers readers to other registered investment advisers and shares in the fees they receive from referred clients, which creates a conflict of interest. Please see our Form ADV Part 2A and consult your own financial advisor before investing.
What Serious Investors Are Watching
Dive into expert interviews, market analysis, and long-form content built to help serious investors think long-term.
Gold IRAs Explained: What the Rules Allow and What They Cost
An annual account fee is easy to spot. The extra amount built into a gold...
Uranium Spot vs Term Prices: Why the Headline Price Isn’t What Most Utilities Pay
Uranium headlines quoted $91.55 a pound at the end of October 2026. Reactor owners in...
REITs Explained: How Real Estate Investment Trusts Work
A REIT lets you own a share of real estate income without owning a building....
Enjoyed This? Get More Insights
Expert insights and curated opportunities, delivered to your inbox.
Ready to Position for What's Coming?
Whether you're still learning or ready to act, your next step starts here.
- Independent
- Macro-Informed
- Real Asset Focused
The Wealthion Network
By subscribing, you agree to receive Wealthion emails. Unsubscribe anytime.
The Wealthion Network
By subscribing, you agree to receive Wealthion emails. Unsubscribe anytime.
Network Discussion
Join the Wealthion Network to Comment